Let's Talk About

Regina Real Estate Resource Centre | Market Updates, Buying & Selling Advice

Looking for practical real estate advice without the jargon? Welcome to the Sold by Samantha blog, where you'll find Regina market updates, home buying and selling tips, neighbourhood guides, and local insights to help you make confident real estate decisions. Whether you're buying your first home, preparing to sell, or simply keeping an eye on the market, you'll find straightforward information designed specifically for Saskatchewan homeowners and buyers.

RSS

The Fall Home Reset: Cleaning + Winterizing Your Home

There’s something about September that makes me want to reset everything. It really feels more like a new year to me than January ever has. We’re all starting new season of life with new routines, sports, and more.

The windows are open, the house finally isn't fighting for its life against the summer heat, and I'm somewhere between desperately hanging onto summer and enjoying my first Pumpkin Spice Latte.

But we also live in Saskatchewan, which means we all know what’s coming.

Winter. 

And while I am absolutely not suggesting we rush it, fall is the perfect time to give your home a little reset and tackle a few of those maintenance jobs that are much less enjoyable once you’re doing them in mittens.

So before the snow falls, here are a few things worth checking off around your home.

OUTSIDE: PUT THE YARD TO BED

Clean Out Your Gutters + Downspouts

Once the leaves have fallen, clear out your gutters so melting snow and spring runoff have somewhere to go. While you’re there, make sure your downspouts are still directing water well away from your foundation.

Do One Last Grading Check

Take a walk around the perimeter of your house and make sure the ground is still sloping away from your foundation. If anything has settled over the summer, fall is a good time to address it before the spring melt.

Drain + Store Garden Hoses

Disconnect your hoses, drain them completely and store them somewhere protected for winter. If your exterior taps have interior shut-offs, turn those off and drain the remaining water from the line.

Frozen pipes are not the kind of winter surprise we're looking for.

Clean Up the Yard

Put away planters, garden décor and anything else that probably won't appreciate being buried under Saskatchewan snow for six months. Clean and cover your outdoor furniture, tidy garden beds and give the lawn one final mow if needed.

Check Trees + Shrubs

Trim dead or damaged branches, particularly anything hanging close to your house, garage or power lines. Heavy snow and prairie winds have a way of finding the branch you meant to deal with.

Winterize Your Sprinkler System

If you have underground sprinklers, make sure they're properly blown out before temperatures consistently dip below freezing.

INSIDE: THE FALL RESET

Spring cleaning gets all the attention, but I might actually prefer a fall reset.

We’re about to spend a lot more time inside, so this is my excuse to make everything feel cozy, clean and slightly more put together before hibernation season begins.

Wash the Windows

Give the glass, screens, sills and tracks a good clean before closing everything up for winter. You’ll appreciate every bit of sunlight you can get come January.

Swap the Seasonal Stuff

Pack away the beach towels, sandals and summer gear and make room for coats, boots, mittens and the lost single gloves every family somehow has.

It's also a great time to donate anything that didn't get worn this summer rather than storing it for another year.

Give the Entryway Some Love

Our entrances work hard through a Saskatchewan winter. Clear out anything you don't need, wash the mats and make sure you have somewhere practical for wet boots, coats and all that winter gear.

Your January self will thank you.

Refresh the Cozy Stuff

Wash your throw blankets, duvet covers, pillows and area rugs. Then bring out the heavier blankets, warmer bedding and all the cozy textures that make being inside feel a little more intentional.

HOME MAINTENANCE: BEFORE IT GETS REALLY COLD

Change Your Furnace Filter

Your furnace is about to become one of the hardest-working things in your house. Replace the filter and consider having your furnace serviced and your ducts cleaned if it's due.

Check Your Smoke + Carbon Monoxide Detectors

Test every detector and replace batteries where needed. With furnaces and fireplaces coming back into regular use, this is an especially important fall check.

Check Windows + Exterior Doors

Feel for drafts and inspect weather stripping and caulking. Small gaps might not seem like much in September, but you'll definitely notice them when it's -30°C.

Inspect Your Roof + Exterior

Take a look for loose or damaged shingles, flashing, siding and anything else that should be repaired before snow and ice arrive.

Check Your Sump Pump

Spring gets most of the sump-pump attention, but fall is another good time to make sure everything is working properly before the ground freezes and eventually starts its next thaw cycle.

Clean Your Dryer Vent

Not glamorous, but important. Clear lint from the dryer vent and exterior exhaust so your dryer can operate safely and efficiently.

AND THEN... ENJOY FALL

Once the gutters are cleaned, the hoses are put away and you've accepted that patio season has an expiration date, you have my full permission to light the fall candle, make something unnecessarily pumpkin-flavoured and enjoy the three perfect weeks Saskatchewan gives us between too hot and why is my face freezing?

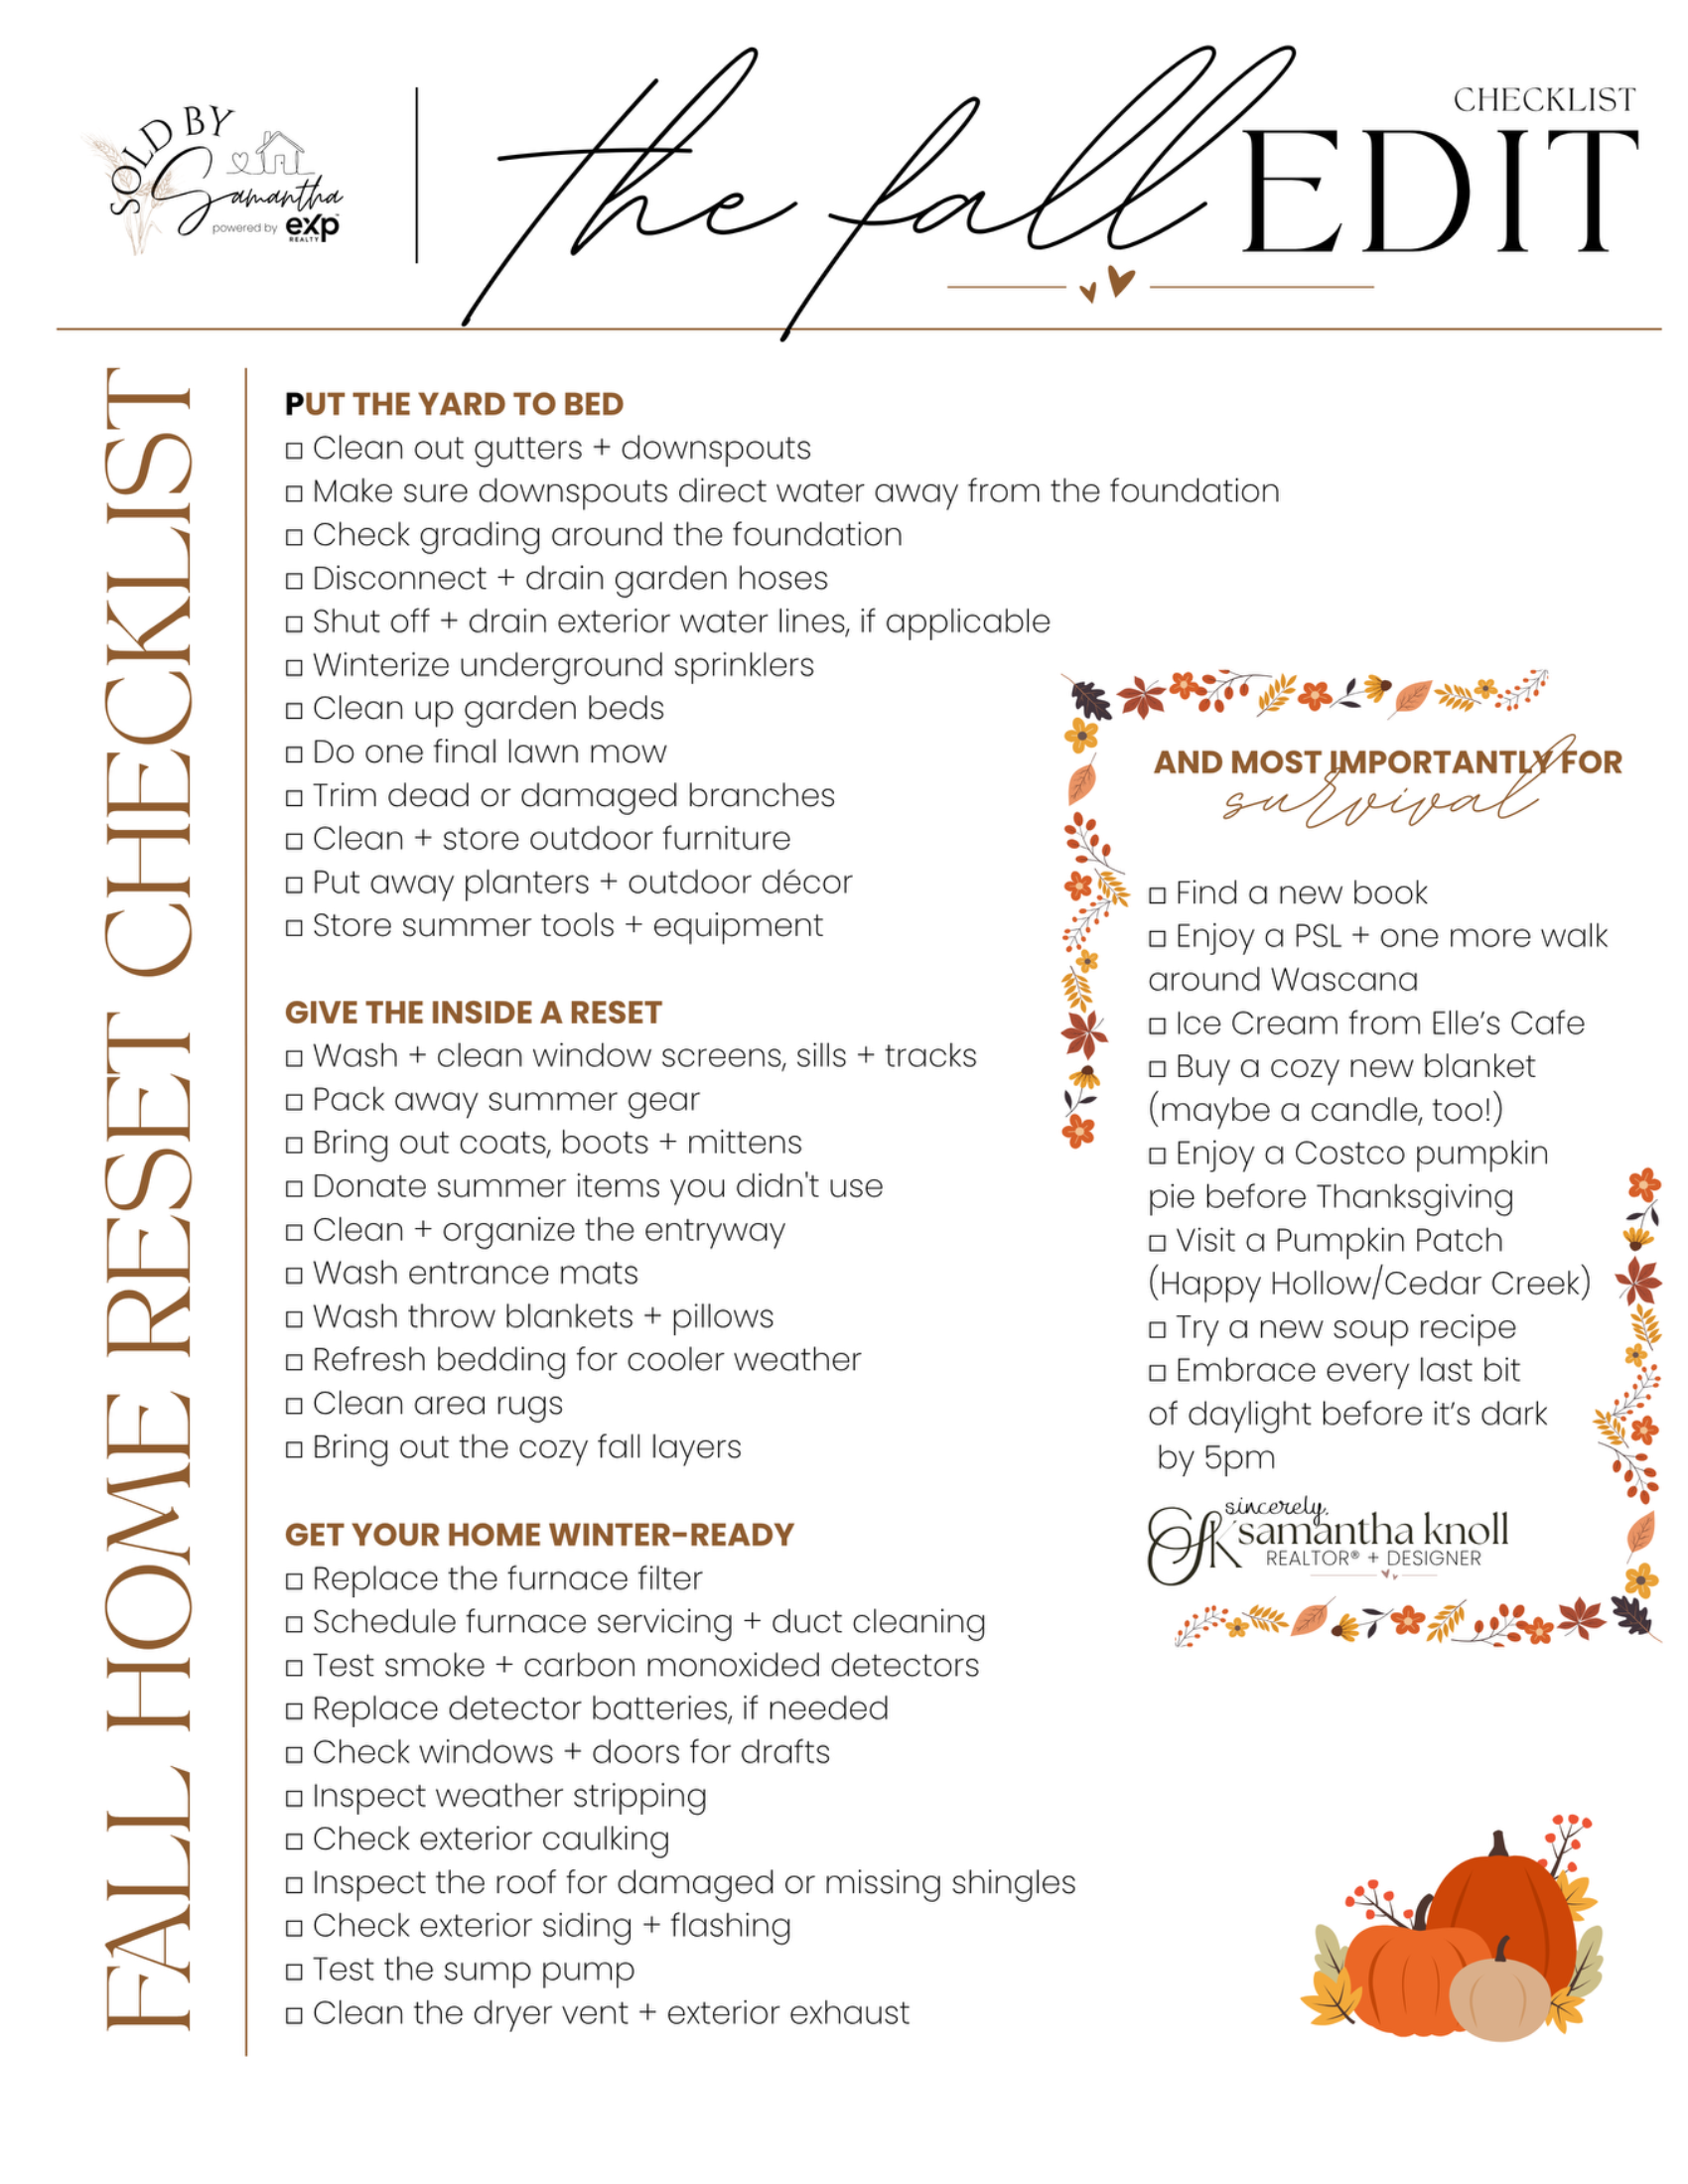
You don't have to do everything in one weekend, either. Pick away at the list while the weather is nice and future-you will be very grateful when the first real snowfall arrives. And if you’re like me, here’s a list you can print off. 
And until then?

I'm keeping the patio furniture out for as long as humanly possible. 🫶🏽

Sincerely, Samantha

Read

Why Your Asking Price Might Be the Most Important Marketing Decision You'll Make

There is one conversation that almost every seller wants to have. "So... what if we listed a little higher just to see what happens?" It's a fair question. After all, if someone is willing to pay more, why wouldn't you ask for more?

The problem is that real estate doesn't quite work like a garage sale. You don't put a price tag on your home hoping someone offers less. You also don't throw a number at the wall to see if it sticks. Your asking price isn't just a number.

It's part of your marketing strategy.

Buyers Decide if Your Home Is Worth Seeing in About 30 Seconds

Before buyers ever walk through your front door, they've already made dozens of decisions.

They've looked at the photos. They've compared your home to similar listings. They've looked at the neighbourhood. They've probably sent it to their spouse, their parents, and three friends for opinions. Then they decide one thing…

"Is this worth seeing?"

If your home feels overpriced compared to everything else they're looking at, they often don't book a showing at all. They simply move on to the next listing.

You can't sell a home to someone who never walked through the front door.

"We Can Always Reduce the Price Later..."

Technically... yes. Strategically... not usually.

The first week your home is on the market is when it receives the most attention. Buyers who have been waiting for something like your home are notified almost immediately. That excitement is incredibly valuable.

If the price isn't right from the beginning, you've essentially spent your biggest marketing opportunity introducing buyers to a home they weren't interested in. By the time the price comes down, many buyers are already asking themselves another question.

"What's wrong with it?"

Nothing may be wrong at all. It simply started in the wrong place. And then convincing buyers that it was just price (especially in a market like Regina’s with our gumbo soil) is almost impossible. 

Pricing Isn't About Getting Less

This is probably the biggest misconception I hear.

When I recommend a strategic asking price, I'm not trying to convince someone to sell their home for less. I'm trying to create enough interest that buyers compete for it.

Sometimes that means one offer. Sometimes it means multiple offers. Sometimes it means buyers are willing to pay more than they originally planned because they don't want to lose the home.

Ironically, some of the strongest sale prices happen because the asking price encouraged competition, not because it scared buyers away.

Your Neighbour's Home Isn't Always the Best Comparison

"But my neighbour listed for..." I hear this one a lot, too. Every home is different. The layout. The updates. The condition. The lot. The location within the neighbourhood.

Even something as simple as backing onto a busy road versus a quiet park can influence value.

Pricing isn't about finding the highest number someone else listed at. It's about understanding what today's buyers are willing to pay for your home.

The Goal Isn't to "Win" the Listing

One of my favourite sayings in real estate is this:

You can price a home anywhere you want. The market gets the final vote. My job isn't to tell you the highest number possible because it sounds exciting.

It's to help you understand where your home sits in today's market, explain why, and create a strategy that gives you the best chance of achieving the strongest result. Sometimes that means listing at exactly what you expected. Sometimes it doesn't. Either way, the goal stays the same. Sell your home for the best possible price, in the least amount of time, with the fewest headaches.

Because that's a much better story than saying... "Well... at least we tried."

The Right Asking Price Is Your Strongest First Impression

Setting the right asking price isn't about guessing. It isn't about chasing the highest number or hoping the market proves you right. It's about understanding buyer behaviour, knowing what's happening in your neighbourhood today, and creating a strategy that gives your home the strongest chance of standing out from the moment it hits the market. Because in real estate, first impressions matter, and your asking price is one of the biggest first impressions you'll make.

Curious what your home would realistically sell for in today's Regina market?

I'd be happy to put together a complimentary market evaluation. No pressure, no sales pitch, and no obligation. Just honest advice, current market data, and a pricing strategy that's built around your home, not just a number.

Sincerely, Samantha

Read

Why Does My REALTOR® Need to FINTRAC Me?

And no, your REALTOR® isn’t just being nosy. 😉

You’ve found the house. You’re ready to write the offer. And then your REALTOR® starts asking for your ID, occupation, and information about where your deposit is coming from. 

It can feel a little… invasive?!? But I promise, we’re not being nosy. We’re doing our job. Welcome to FINTRAC.

First Things First: What is FINTRAC?

FINTRAC stands for the Financial Transactions and Reports Analysis Centre of Canada. That is a very long name for a federal agency that helps detect, prevent and deter things like money laundering and terrorist financing in Canada.

Real estate involves large amounts of money changing hands, which means real estate professionals have specific legal obligations under Canada’s anti-money laundering laws.

In plain English? Your REALTOR® is required by law to know who they’re working with and, in certain situations, where the money involved in a transaction is coming from. It isn’t optional, and it isn’t something your REALTOR® made up to add another form to your already impressive pile of paperwork.

So… What Do I Have to Provide?

Depending on your transaction and circumstances, your REALTOR® may need to collect or verify information such as:

  • Your identity

  • Your occupation

  • Information about the source of funds being used in the transaction

  • Information about your deposit

  • Details about who is actually purchasing or selling the property

Sometimes this can feel like a lot of questions, especially when you’ve worked with your REALTOR® before.

Yes, even if we’re friends.

Yes, even if I sold you your last house.

Yes, even if I absolutely, positively know who you are. 

There are still FINTRAC requirements I have to follow.

Why Does the Source of Funds Matter?

This is probably the part that gets the most raised eyebrows. If I ask where your deposit or purchase funds are coming from, I’m not asking because I’m curious about your bank account. I’m asking because real estate professionals have obligations to document certain financial information and watch for transactions that may be unusual or suspicious.

For most buyers, the answer is incredibly ordinary: savings, proceeds from the sale of another home, investments, a gift from family, financing, or some combination of those.

We simply need to document it appropriately.

What Happens to My Information?

Your information isn’t collected for marketing purposes or because your REALTOR® wants to keep tabs on your finances.

FINTRAC requires real estate brokerages and professionals to collect and retain certain records as part of their legal compliance obligations. Your REALTOR® should also be able to explain what they need, why they need it and how the information is being collected.

And if something feels unclear? Ask. I would much rather explain why I’m requesting something than have you wondering why on earth I suddenly need to know your occupation while you’re trying to buy a house.

The Samantha-Sized Version

FINTRAC sounds intimidating. For the vast majority of clients, it really isn’t. It essentially boils down to this:

Real estate involves a lot of money, Canada has rules designed to help prevent that money from being used for illegal purposes, and REALTORS® are one of the professions required to help follow those rules.

So when I send you a secure link asking you to verify your identity or ask a few questions about your funds, there’s no red flag beside your name. It’s simply part of buying or selling real estate in Canada.

A little paperwork. A few questions. One more box checked. Then we can get back to the much more exciting stuff… like finding you a house. 🤎


Have questions about buying or selling in Regina, Saskatoon or Southern Saskatchewan? You never have to know all the answers before reaching out. That’s quite literally what I’m here for.

Sincerely, Samantha

Read

Spousal Buyouts: A mortgage option with understanding | Mortgage Minute with Candice Carr

Whether you are a friend of someone going through a separation, or the person navigating the separation yourself, there is something valuable here for you. A separation brings no shortage of difficult decisions, and one of the biggest is what to do with the family home. Selling and dividing the proceeds may be the right answer, but it is not the only one. If one spouse wants to stay, a spousal buyout may make it possible to purchase the other person’s share and place the home and mortgage in the remaining spouse’s name.

To the friend who knows someone separating

You may be the first person they turn to for a listening ear or practical advice. Sharing clear information about options like a spousal buyout can reduce overwhelm and help them see that keeping the family home is sometimes achievable. Pointing them toward experienced guidance early can make a meaningful difference at a stressful time.

To the person going through a separation

You do not have to figure this out alone. Experienced brokers and agents work with these situations regularly and can walk you through the numbers, the paperwork, and the realistic possibilities so you know what options exist. There are solutions available, and having the right support can bring a measure of certainty when so much else feels uncertain.

More than a standard refinance

In a conventional refinance, homeowners are generally limited to borrowing up to 80% of their home’s value. A qualifying spousal buyout may instead be treated as a purchase transaction, potentially allowing financing above that limit through an insured mortgage.

For example, on a home valued at $600,000:

  • A conventional refinance would generally be limited to $480,000, or 80% of the home’s value.

  • A qualifying spousal buyout could potentially provide up to $565,000 before the mortgage-insurance premium.

  • That could make up to $85,000 in additional financing available to complete the buyout or address eligible joint debts included in the separation agreement.

For illustration, at a mortgage rate of 4.50% and a 25-year amortization, the monthly payment would be approximately $2,657 under the conventional refinance limit, compared with about $3,252 if the maximum spousal-buyout amount and mortgage-insurance premium were financed.

These figures are for illustration only, as the amount available and monthly payment will depend on the home’s appraised value, the required buyout, the existing mortgage, applicable insurance premiums and the rate available when the financing is arranged.

The funds are generally used to pay out the existing mortgage and the departing spouse’s agreed share of the equity. Depending on the lender and mortgage insurer, certain jointly held debts addressed in the separation agreement may also be included.

What lenders will consider

The spouse keeping the home must still qualify for the new mortgage based on their income, credit, other debts and the applicable mortgage stress test.

Child or spousal support received may help with qualification when it is properly documented and expected to continue. Some lenders may use 100% of qualifying support income, while others apply different limits or documentation requirements. Support payments being made must also be included when the lender assesses the borrower’s obligations.

Lenders will typically ask for:

  •  A signed separation agreement setting out the division of the property, debts and any support obligations;

  • Documentation supporting the transfer and agreed buyout amount;

  • An appraisal confirming the home’s current value; and

  • The legal transfer of the departing spouse’s interest in the property.

A signed separation agreement can also be important if either spouse plans to purchase another home. A signed separation agreement can also be important if either spouse plans to purchase another home. Requirements will vary by lender and province, and a signed agreement documenting the borrower’s financial obligations may be needed before completing financing connected to a separation..

There may also be mortgage-insurance premiums, legal fees, appraisal costs and, depending on the province and circumstances, land-transfer or registration costs. Any penalty for breaking the existing mortgage must also be included in the calculation.

This may sound complex, but you don’t have to navigate it alone. I have the knowledge and resources to guide you through the financing process, explain what documentation is needed and help keep the transaction moving at each stage.

Start the conversation early

If you or someone you know is going through a separation, reach out before finalizing the agreement or making decisions about the property. I can confidentially review the estimated buyout, qualification requirements and potential monthly payments so you have a clearer picture of what may be possible.

Connect with Candice

Candice Carr | Mortgage Broker


(306) 531-6880
candice@candicecarr.ca

https://candicecarr.ca

Read
The Saskatchewan REALTORS® Association (SRA) IDX Reciprocity listings are displayed in accordance with SRA's MLS® Data Access Agreement and are copyright of the Saskatchewan REALTORS® Association (SRA).
The above information is from sources deemed reliable but should not be relied upon without independent verification. The information presented here is for general interest only, no guarantees apply.
Trademarks are owned and controlled by the Canadian Real Estate Association (CREA). Used under license.
MLS® System data of the Saskatchewan REALTORS® Association (SRA) displayed on this site is refreshed every 2 hours.